
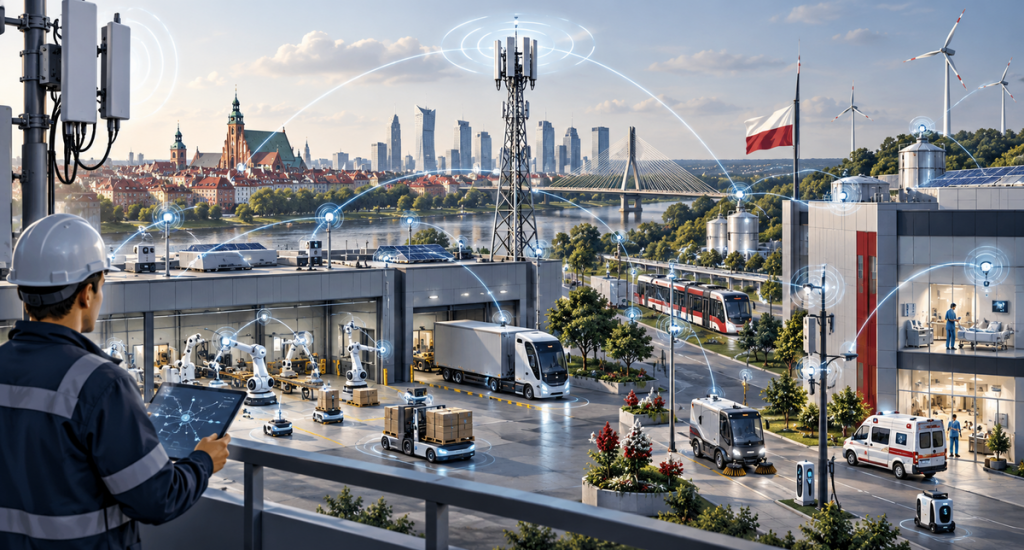
Poland’s 5G story has moved beyond the speculative phase. What was once framed mainly as a telecom upgrade is becoming something more consequential: a layer of national business infrastructure that will influence how factories digitize, how logistics networks operate, how public services modernize, and how technology investors think about long-term commercial deployment. That shift matters because 5G is not valuable simply for faster consumer mobile service, its real strategic significance lies in what it enables across enterprise environments where uptime, latency, device density, and data flow start to shape operating performance.
The spectrum picture is now materially more advanced than many earlier market summaries suggested. Poland completed its 3.6 GHz auction in 2023, issued reservation decisions and radio licenses in late 2023 and early 2024, and then concluded the 700/800 MHz auction in March 2025. In practical terms, that gives the market both a mid-band foundation for capacity and a lower-band layer better suited to broader geographic reach, including less dense areas.
That does not mean the market is fully mature. It means Poland is entering a more commercially relevant stage, one in which operators, industrial users, municipalities, software providers, and infrastructure vendors can move from abstract positioning to actual deployment choices. For foreign companies considering Poland, the opportunity is therefore not just to “participate in 5G,” but to decide where along the value chain they can solve real business problems as connectivity improves and enterprise digitization deepens.
Market Landscape
Poland’s 5G rollout is unfolding in a market that already has strong industrial logic for advanced connectivity. The country remains an important European manufacturing location, with major activity in automotive, electronics, machinery, household appliances, and other production-intensive sectors. Public investment and trade reporting also point to a broader trend toward Industry 4.0, automation, and technology-heavy projects in manufacturing and logistics. Both 5G and IoT tend to gain commercial traction fastest where production systems, transport operations, and distributed assets already generate a clear need for real-time visibility and tighter control.
The telecom side is also moving from license allocation toward visible network expansion. The European Commission’s 5G Observatory has highlighted T-Mobile Poland’s expansion beyond 4,000 active 3.5 GHz base stations and coverage above half of the population, while also noting activation of 700 MHz 5G after the 2025 auction. The same Observatory has reported Orange Poland beginning 5G standalone trials in Warsaw, which is notable because standalone architecture is the version of 5G most closely associated with enterprise-grade capabilities such as lower latency, more stable performance, and future network slicing use cases.
The IoT ecosystem, meanwhile, is not starting from zero. Poland already has commercial NB-IoT offerings for smart-city applications, and public smart-city data platforms are operating in the market. In other words, the country already has working examples of connected devices being used for environmental monitoring, utilities, and municipal services. What 5G changes is not the existence of IoT itself, but the scale, responsiveness, and range of enterprise use cases that can be supported as networks improve.
For investors and operators, the commercial takeaway is straightforward. Poland is no longer just preparing for 5G, it’s building the conditions under which connectivity can become operational infrastructure for industrial, logistics, municipal, and service-sector applications. The strategic question is now less about whether 5G will matter, and more about where monetization will happen first and where deployment friction will remain highest.
Opportunities and Challenges
Smart manufacturing and private industrial networks
Manufacturing is one of the most credible commercialization paths for 5G-enabled IoT in Poland. The country’s production base, supplier ecosystems, and growing Industry 4.0 focus create a practical case for connected sensors, machine monitoring, predictive maintenance, robotics coordination, and real-time production visibility. In that setting, 5G becomes valuable not because it is new, but because it supports more responsive and more reliable operations than legacy connectivity models can always provide.
The challenge is that industrial buyers do not purchase connectivity for its own sake, they buy solutions that reduce downtime, improve throughput, strengthen quality control, or lower maintenance costs. That means vendors entering Poland need to position themselves around measurable operating outcomes, not around generic claims about digital transformation. In this market, the strongest 5G propositions are likely to be those linked to identifiable plant-level use cases.
Logistics, transport, and distributed asset visibility
Poland’s role in European logistics gives IoT strong commercial relevance in fleet tracking, route optimization, cold-chain monitoring, warehouse visibility, and infrastructure-linked transport services. Trade and investment sources continue to describe Poland as a strategically located production and distribution base within Europe, which makes logistics digitization especially important. Better connectivity does not automatically transform transport operations, but it improves the business case for connected fleets, sensor-rich cargo monitoring, and software-led coordination across dispersed networks.
Here, too, the opportunity comes with execution risk. Logistics buyers usually care less about the radio layer than about system integration, interoperability, installation discipline, and data usefulness. Companies that enter the market with hardware only or software only may find that customers increasingly prefer integrated offers that combine devices, connectivity, analytics, security, and implementation support.
Smart cities and public infrastructure
Municipal and utility-style use cases are already visible in Poland, especially where connected sensors support water, air, mobility, or environmental monitoring. Existing NB-IoT offerings and public smart-city data environments show that public-sector digitization is not merely conceptual. As 5G capacity and coverage improve, some cities and service providers will have stronger options for connecting more complex assets and managing larger data flows across urban infrastructure.
Public-sector commercialization usually moves more slowly than private enterprise deployment. Procurement cycles, budget structures, integration complexity, and governance requirements can all delay rollout. For many foreign firms, municipalities may be an attractive long-term channel, but not always the fastest route to early revenue. A better first step may be to build reference cases in industry or logistics and then use those examples to support later public-sector entry. This is an inference based on the deployment pattern visible across industrial and smart-city markets rather than a formal rule.
Cybersecurity, screening, and compliance discipline
As the market matures, regulation will be more important. Poland’s spectrum allocation process has incorporated security and integrity requirements for telecom infrastructure, and the broader legal environment includes the National Cybersecurity System framework as well as screening rules for certain investments tied to strategic sectors and critical infrastructure. For telecom and infrastructure-adjacent investors, that means regulatory diligence should be built into market entry planning from the start rather than treated as a later legal cleanup exercise.
Tax and innovation incentives also deserve attention. Poland’s standard corporate income tax rate is 19%, with a reduced 9% rate available in qualifying cases, and the country continues to promote innovation through R&D relief and the IP Box regime. For companies building software, industrial platforms, connected-device IP, or local engineering capability, that incentive framework can materially improve the economics of a Polish operating model.
Strategies and Partnerships
Foreign entrants should resist the temptation to approach Poland’s 5G and IoT market as a pure telecom play. In many cases, the better strategy is to enter through a vertical problem, then build outward. A company that can solve a specific manufacturing, warehouse, fleet, utility, or monitoring problem will often have a stronger position than one offering broad but abstract connectivity promises.
Three strategic approaches stand out:
- Anchor the offer in a sector with clear operating pain points – Manufacturing, logistics, and infrastructure-heavy services are more likely to generate near-term demand than undifferentiated horizontal positioning. Buyers in these sectors usually respond to productivity logic, not to technology branding alone.
- Build with local partners who control deployment reality – Depending on the model, that may mean operators, systems integrators, industrial software firms, automation specialists, device assemblers, or municipal technology partners. In Poland, execution often depends less on having the most elegant concept than on having the right local route into real installations.
- Treat cybersecurity and investment structuring as part of go-to-market design – Telecom-adjacent and infrastructure-related projects can trigger more scrutiny than standard software launches. A clean compliance model, well-defined data handling, and early legal review can reduce friction and make partnership discussions easier.
The broader strategic point is that Poland’s 5G opportunity will not be captured by spectrum ownership alone. Much of the value will accrue to companies that can translate connectivity into measurable operational advantage. That includes vendors of industrial software, cybersecurity layers, analytics platforms, connected devices, private-network solutions, integration services, and managed support models. The market is becoming more attractive precisely because it is moving from network buildout toward commercial application.
How Expand2Poland Can Help
Expand2Poland supports clients with:
- Market and sector-entry analysis for 5G and IoT opportunities in Poland
- Partner identification across operators, industrial players, and technology integrators
- Regulatory and investment-screening guidance
- Localization of commercial strategy for Polish enterprise customers
- Support in structuring market entry, partnerships, and growth plans
For companies looking at Poland’s next wave of digital infrastructure, the real opportunity is not connectivity alone. It is the chance to build businesses around the industries, assets, and public systems that connectivity is beginning to reshape.
The information provided in this article is for general informational and educational purposes only and does not constitute legal, financial, or tax advise.